Business income under the simplified tax regime has increased by almost 19%.
02.10.2026 09:03:47 304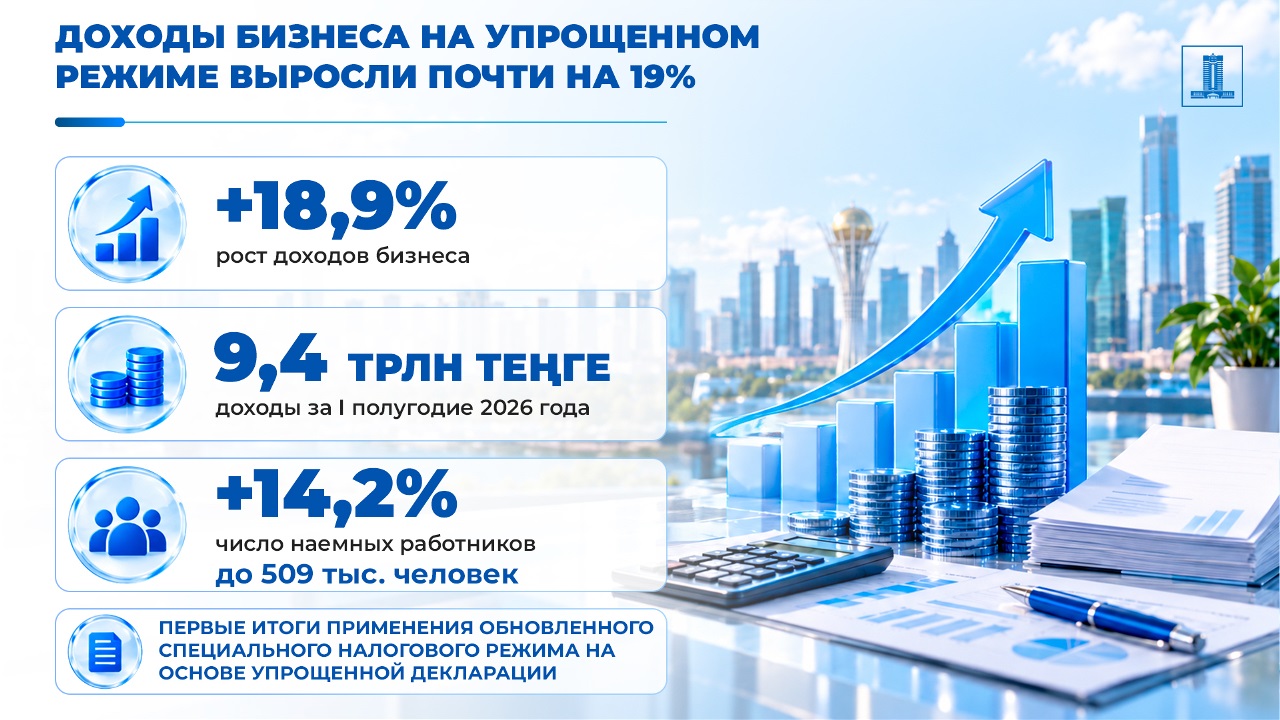
The government policy is consistently aimed at creating favorable conditions for entrepreneurship, reducing administrative burdens, and establishing clear rules for doing business.
One of the steps in this direction has been the improvement of tax legislation. Since January of the current year, the new Tax Code has come into force, within which special tax regimes have been optimized.
One of the most sought-after is the special tax regime based on the simplified declaration. The initial results of its implementation show a positive trend in the main performance indicators of entrepreneurs.
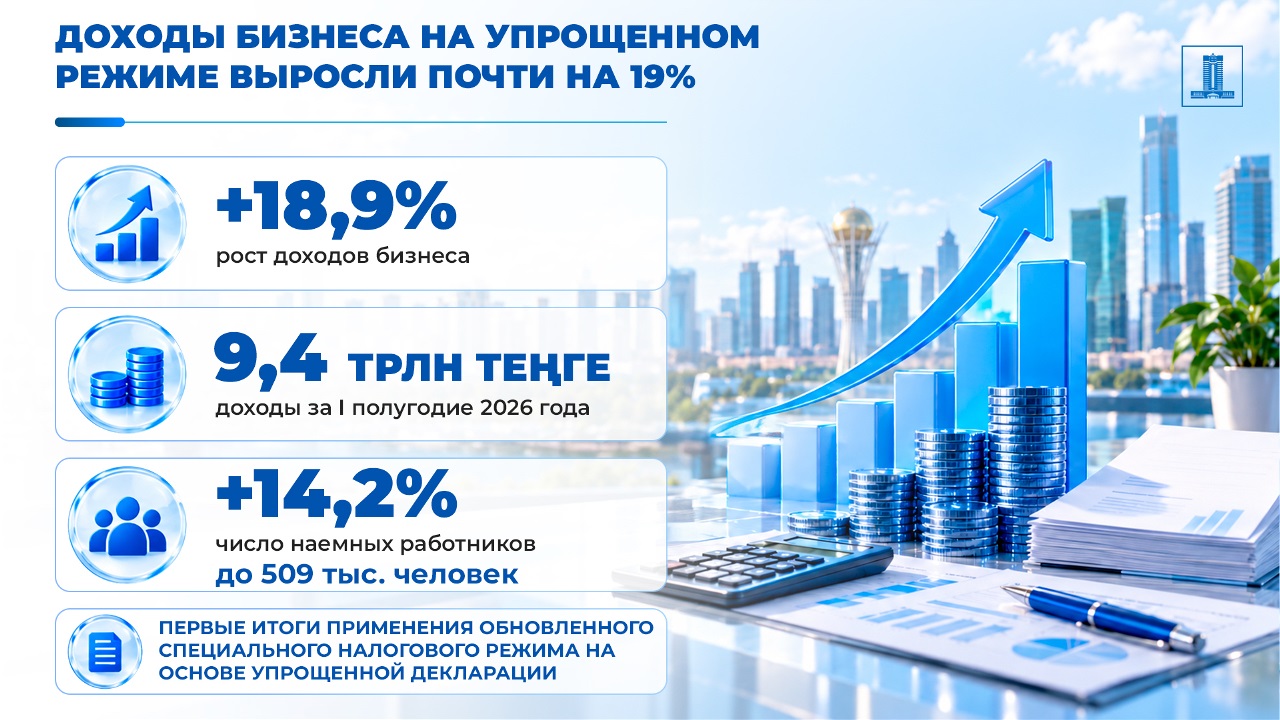
According to the results of the first half of the current year, the income of businesses using this regime amounted to 9.4 trillion tenge. Compared to the same period last year, it has increased by 18.9% — from 7.9 trillion tenge.
Positive dynamics are also observed in the employment indicators of entrepreneurs applying this regime. The number of hired workers increased by 14.2% — from 445,000 to 509,000 people. The wage fund grew by 7.2%.
At the same time, the number of business entities without hired employees decreased by 30.5%. The number of entrepreneurs reporting income from zero to 5 million tenge also decreased by nearly a third.
This data was obtained from the results of the first reporting period under the updated regime. In August, entrepreneurs submitted declarations for the first half of the current year for the first time.
The special tax regime based on a simplified declaration can be applied by individual entrepreneurs and legal entities that meet the requirements established by the Tax Code, with an annual income of up to 600,000 MCI.
The rate of individual or corporate income tax is 4%. Local representative bodies have the right to reduce or increase this rate within the limits established by law. The tax and reporting period is half a year.
Entrepreneurs using this regime are also not subject to social tax and VAT, except for VAT on imported goods and VAT for non-residents. Initial results show an increase in declared business income and employment. At the same time, the number of entrepreneurs without hired employees and entities declaring minimal income is decreasing.
The data obtained allows for the assertion of the first positive results from changes to special tax regimes. Their further impact will be assessed as data accumulates in subsequent reporting periods.
Source : https://www.gov.kz/memleket/entities/minfin/press/news/details/1302790?lang=ru