News
More
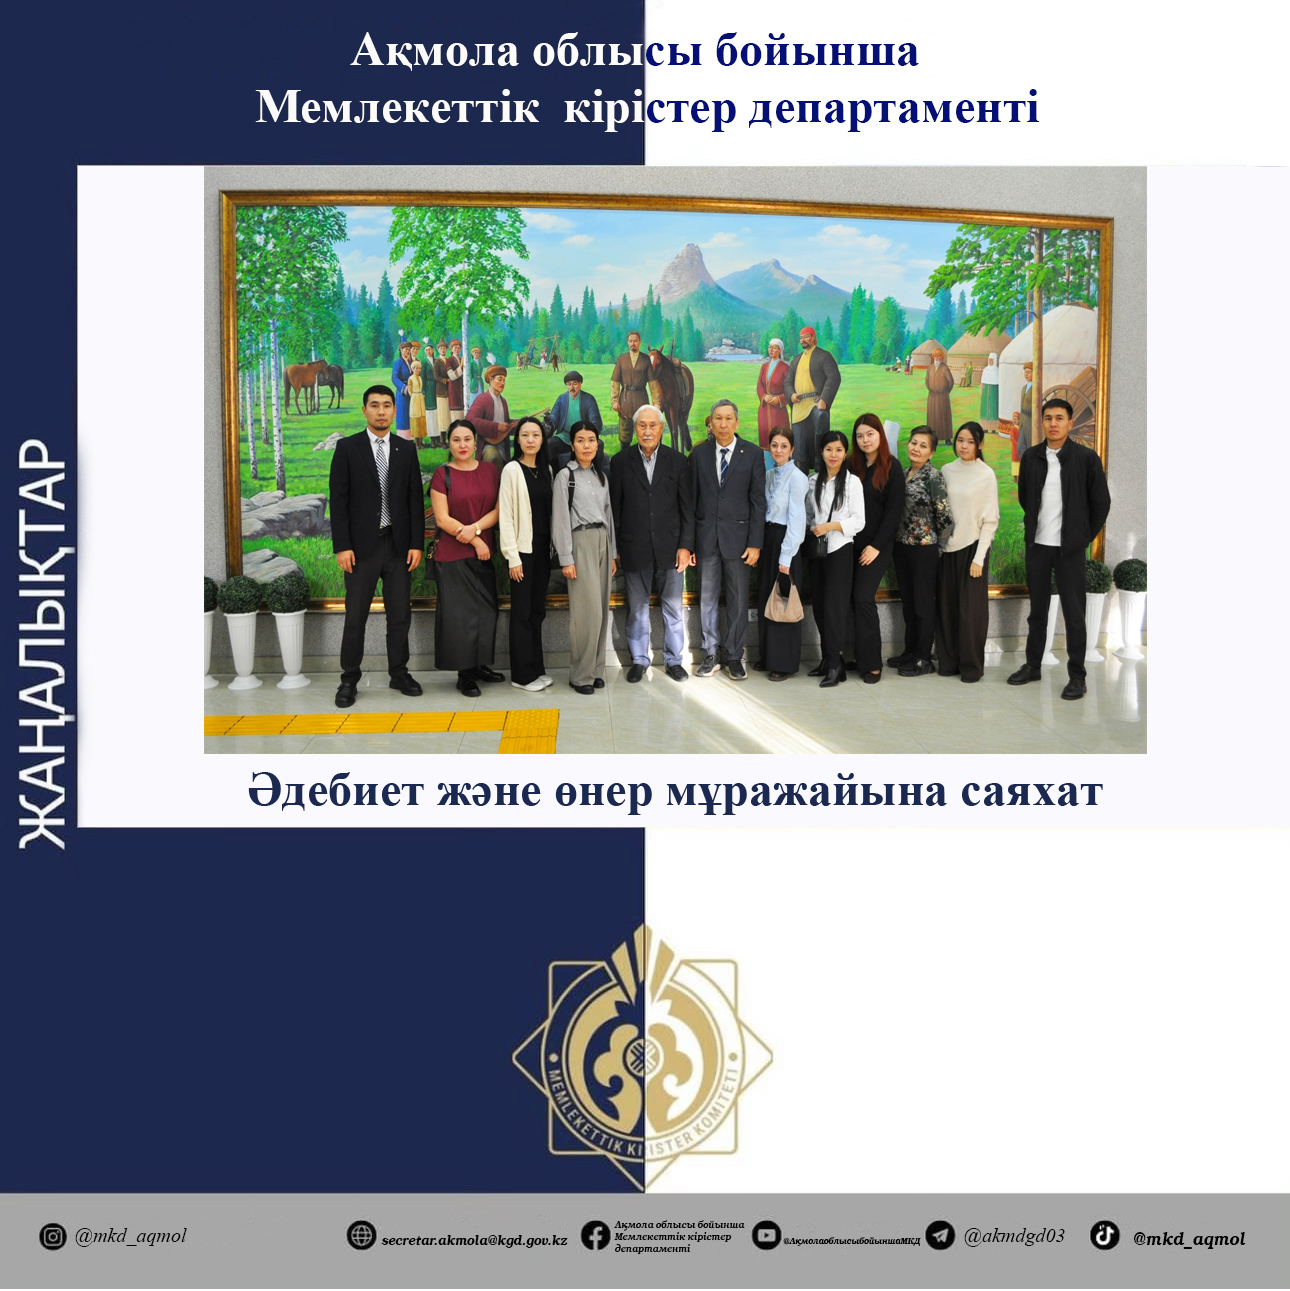
Excursion to the Museum of Literature and Art
16.11.2026
On October 22, ahead of Republic Day, employees of the State Revenue Department for the Akmola Region visited the regional Museum of Literature and Art.Museum expositions tell about folklore, pre-revolutionary and modern literature, about the art of the pen as a whole.Of great interest is a valuable historical rarity of the 16th - 17th centuries - a copy of the manuscript of the book by Khoja Ahmed Yaasaui "Diuani hikmet" (Spiritual Knowledge).Department employees saw Akan's adalbakan cepi, Singer sewing machine and a mirror of his beloved Aktokta. No less valuable and interesting personal belongings, manuscripts, literary and artistic works of Kazakh akyns - improvisers, singers Birzhan sal, Ykili Ybyyrai, Baluan Sholak, Koken Shakeev, famous writers Zhumagali Sain, Saken Zhunusov and many other prominent figures of literature and art of Kokshetau landAndesh Kurmanbayev, a veteran of the tax service, who took part in the event, noted that the exhibits and artifacts of the Museum characterize the national culture, ethnographic values and identity of the Kazakh people.Source : https://www.gov.kz/memleket/entities/kgd-akmola/press/news/details/1316062?lang=ru
The State Revenue Department for the Karaganda Region informs taxpayers about the compulsory termination of their activities
16.11.2026
📢 The State Revenue Department for the Karaganda Region informs taxpayers about the compulsory termination of their activities⚖️ In accordance with Article 109 of the Tax Code of the Republic of Kazakhstan, the compulsory termination of activities is предусмотрено for taxpayers included in the register of inactive taxpayers who meet the conditions established by law.🔎 Who is subject to compulsory termination of activities?Pursuant to paragraph 1 of Article 109, a taxpayer included in the register of inactive taxpayers is subject to compulsory termination of activities if, during the limitation period, the taxpayer simultaneously meets the following conditions:1️⃣ Has not independently submitted tax returns.2️⃣ Has not carried out export or import transactions.3️⃣ Has not made payments and/or transfers of money through bank accounts.4️⃣ Has not been registered for value-added tax (VAT) purposes.5️⃣ Has not acted as the head and/or founder of another legal entity or as a participant in joint entrepreneurship.6️⃣ Has not suspended the submission of tax returns.7️⃣ Has not owned property subject to property tax, vehicles subject to vehicle tax, or land subject to land tax, except for taxable items belonging to individuals.8️⃣ Has no outstanding social payment liabilities.9️⃣ Has no outstanding tax liabilities, payments to the budget, customs duties or taxes exceeding six times the monthly calculation index (MCI) in effect as of January 1 of the relevant financial year.⚠️ In which cases do these provisions not apply?The provisions of the first part of paragraph 1 of Article 109 do not apply to taxpayers:🔹 subject to tax monitoring;🔹 carrying out activities under a subsoil use contract;🔹 having outstanding notifications on the elimination of violations identified through desk audits or tax inspections, or notifications considered fulfilled through the submission of explanations, where such violations exist;🔹 subject to measures (seizures or restrictions) imposed by enforcement officers and/or other authorized bodies;🔹 who are or were parties to a foreign exchange contract relating to exports or imports for which foreign exchange control procedures aimed at the repatriation of national and/or foreign currency have not been completed;🔹 who have made payments and/or transfers of money through bank accounts during the limitation period.📌 What else should be taken into account?The period taken into account when including a taxpayer in the register of inactive taxpayers is also included in the period considered for the compulsory termination of activities.🏛️ How is compulsory termination of activities carried out?In accordance with paragraph 2 of Article 109 of the Tax Code of the Republic of Kazakhstan:⚖️ The compulsory termination of a taxpayer’s activities is carried out by the tax authority on the basis of a court decision that has entered into legal force, in accordance with the requirements of the laws of the Republic of Kazakhstan.📄 A taxpayer whose activities have been compulsorily terminated on the basis of a court decision that has entered into legal force is deregistered with the tax authority in accordance with the established tax registration procedure.✅ The State Revenue Department for the Karaganda Region recommends that taxpayers fulfil their tax obligations on time, submit tax returns within the prescribed deadlines, and ensure that their registration status remains up to date.🤝 Compliance with tax legislation is an important condition for the proper fulfilment of tax obligations. Source : https://www.gov.kz/memleket/entities/kgd-karaganda/press/news/details/1316065?lang=ru
Pilot Project for Business Support and Assistance Centres.
16.11.2026
The Department of State Revenue for Astana hereby informs that, starting from 1 September 2026, JSC “Entrepreneurship Development Fund ‘Damu’” will implement a pilot project to establish Business Support and Assistance Centres in the cities of Astana, Almaty and Shymkent, as well as in the Aktobe and North Kazakhstan regions.The Centres provide comprehensive support to small and medium-sized businesses facing crisis situations. Their operations are based on a “one-stop-shop” principle, whereby entrepreneurs receive assistance in identifying the nature of their problems, developing solutions, and obtaining support in liaising with relevant government authorities and financial institutions.Representatives of the territorial departments of state revenue and the regional Chambers of Entrepreneurs “Atameken” receive entrepreneurs at the Centres in accordance with an established schedule.For further information, please contact the regional branches of the Damu Fund in the regions listed above. Source : https://www.gov.kz/memleket/entities/kgd-astana/press/news/details/1316038?lang=ru
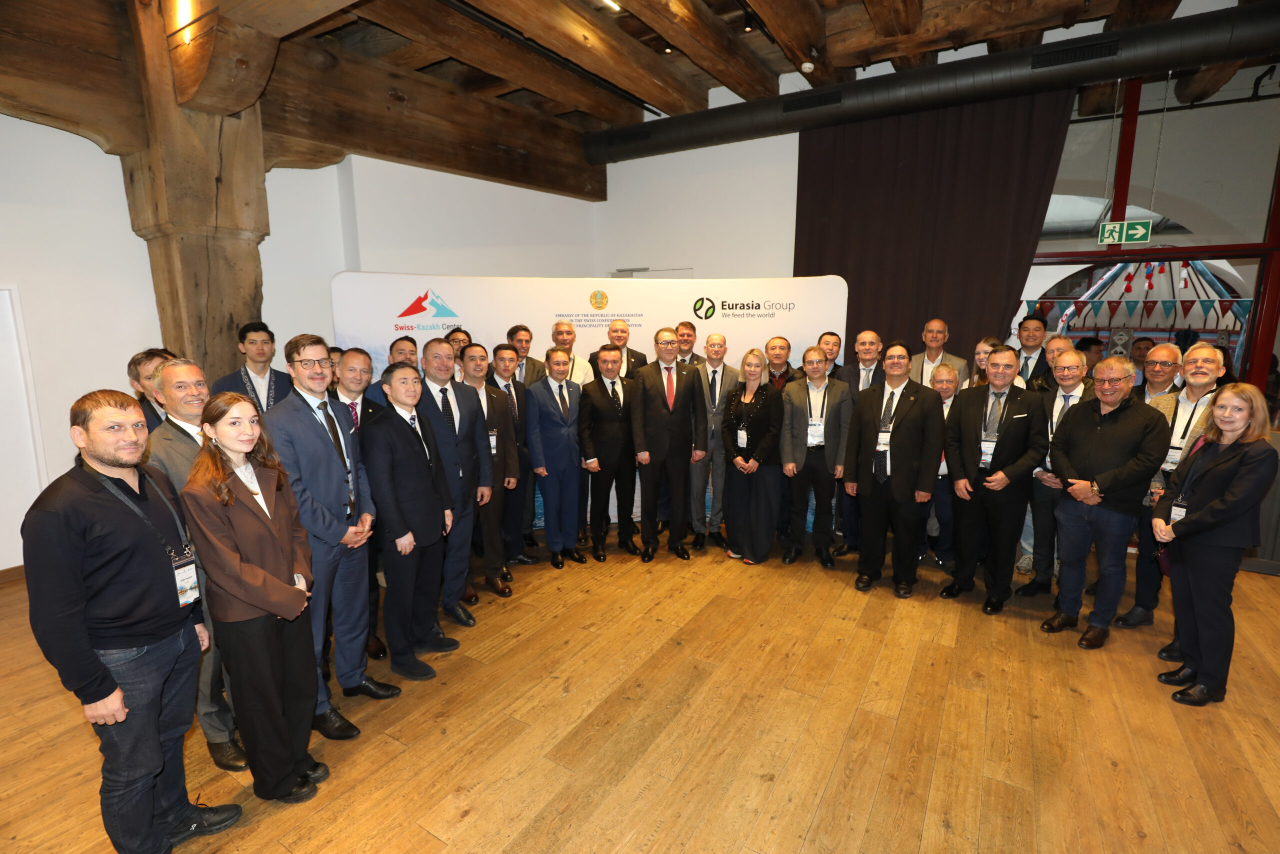
Kazakhstan’s Cultural and Business Centre Opens in Switzerland
15.11.2026
On 21 October 2026, the Swiss–Kazakh Cultural and Business Centre was inaugurated in Schaffhausen, Switzerland. The centre was established on the initiative of Eurasia Group, with the support of the Embassy of the Republic of Kazakhstan in Switzerland, to promote trade, economic and cultural cooperation between the two countries.One of the centre’s key priorities will be to promote Kazakhstani products in Switzerland and other international markets. Particular emphasis will be placed on products from the metallurgical, agro-industrial, food and chemical industries. The centre will facilitate direct business contacts between Kazakhstani producers, foreign importers and retail chains, as well as support the development of investment cooperation. Another dedicated area of its activities will focus on promoting Kazakhstan’s history and culture.The opening ceremony was attended by Arman Shakkaliyev, Minister of Trade and Integration of the Republic of Kazakhstan; representatives of the authorities of the Canton of Schaffhausen; representatives of the Embassy of Kazakhstan in Switzerland and QazTrade JSC; Kazakhstani and Swiss entrepreneurs; and members of the academic community.Speaking at the event, Arman Shakkaliyev emphasised Kazakhstan’s interest in expanding economic cooperation with Switzerland, including attracting technology, developing industrial capabilities and implementing long-term joint projects.Nurlan Kulbatyrov, Chief Executive Officer of QazTrade JSC, presented Kazakhstan’s export and investment potential, as well as existing support mechanisms designed to help domestic producers enter the Swiss market.M. Zakhin, President of Eurasia Group AG, outlined the objectives behind establishing the centre and its role in fostering business ties between entrepreneurs from the two countries.Representatives of the Canton of Schaffhausen highlighted prospects for cooperation with Kazakhstan in business, agriculture and agricultural processing. Opportunities to strengthen scientific, educational and cultural ties were also discussed during the event.Kazakhstan’s Ambassador to Switzerland, K. Sarzhanov, presented key indicators of bilateral economic cooperation. Since 2005, Swiss investment in Kazakhstan has exceeded USD 36.5 billion. In 2025, bilateral trade turnover amounted to USD 1.5 billion.The initiative to establish the centre was launched by Eurasia Group, which operates in Kazakhstan’s agricultural machinery market. The group’s total investment in Kazakhstan has reached USD 88.5 million. These funds have been directed towards developing service infrastructure, purchasing equipment and training specialists. Since 2025, the company has also been working to localise the production of John Deere agricultural machinery in Kazakhstan. Source : https://www.gov.kz/memleket/entities/mti/press/news/details/1315985?lang=ru
AGRICULTURAL COOPERATIVES: WHEN SHOULD I PAY 3%, 6%, OR 20% CPN?
15.11.2026
AGRICULTURAL COOPERATIVES: WHEN SHOULD I PAY 3%, 6%, OR 20% CPN?Starting from January 1, 2026, Kazakhstan has differentiated corporate income tax (CIT) rates for agricultural production cooperatives (SPCs).The main rule: The rate depends not just on the status of the cooperative or the OKED code, but on what exactly it does and where it gets its products from.3%Its products6%SEC activities20%Other activitiesWhen does 3% apply?If the cooperative is a direct producer of agricultural products.Examples:The SEC independently grows wheat and sells the crop.The cooperative breeds cattle and sells the raised breeding young.SEC produces its own milk, processes it into cheese, butter or other dairy products and sells the finished product.Condition: the products must be produced in-house by the cooperative.When is 6% applied?If the SEC carries out cooperative activities provided for by the Tax Code that do not fall under the 3% rate.Examples:The cooperative buys the milk produced by its members, processes it and sells the finished products.SEC harvests, stores, and sells grain grown by cooperative members.The cooperative provides its members with zootechnical and other auxiliary services for the production of agricultural products.The SEC sells to its members goods for the production and processing of agricultural products.Important: products purchased from SEC members do not become products of the cooperative's own production. Therefore, the processing of such raw materials refers to the rate of 6%, not 3%.When is 20% applied?If the SEC receives income from other activities that do not comply with the terms of the 3% or 6% rates.Examples:The SEC buys milk from third-party suppliers who are not members of the cooperative, processes and sells products as part of its independent activities.The cooperative provides commercial zootechnical services to third-party organizations.SEC is engaged in independent trading or other activities not provided for in Article 16 of the Tax Code.For such transactions, the rate is determined taking into account the actual nature of the activity and possible special provisions of the Tax Code.Let's look at one example.SEC Bereke is engaged in the production and processing of milk.Own milk → cheese → saleKPN 3%Milk from SEC members → cheese → saleKPN 6%Milk from third-party suppliers → cheese → saleCPN of 20% if the activity does not fall under preferential categoriesWhat if a cooperative conducts several types of activities at once?It is necessary to keep separate tax records for activities that are taxed at different rates.This means that you need to separately account for the relevant income, expenses and calculate taxable income.Three mistakes to avoid1. Consider that any SEC is automatically entitled to a 6% rate on all income.2. Apply 3% to milk processing only because it was purchased from cooperative members.3. Focus solely on the OKED code, without taking into account the actual nature of the activity.Save this post and share it with the heads of agricultural cooperatives! The correct determination of the CPI rate will help to avoid errors in tax reporting and additional charges.Department of State Revenue for Kostanay regionBasis: Articles 16, 211, 345 and 357 of the Tax Code of the Republic of Kazakhstan dated July 18, 2025 No. 214-VIII.Source : https://www.gov.kz/memleket/entities/kgd-kostanay/press/news/details/1315968?lang=ru
Society
More
Excursion to the Museum of Literature and Art
16.11.2026
On October 22, ahead of Republic Day, employees of the State Revenue Department for the Akmola Region visited the regional Museum of Literature and Art.Museum expositions tell about folklore, pre-revolutionary and modern literature, about the art of the pen as a whole.Of great interest is a valuable historical rarity of the 16th - 17th centuries - a copy of the manuscript of the book by Khoja Ahmed Yaasaui "Diuani hikmet" (Spiritual Knowledge).Department employees saw Akan's adalbakan cepi, Singer sewing machine and a mirror of his beloved Aktokta. No less valuable and interesting personal belongings, manuscripts, literary and artistic works of Kazakh akyns - improvisers, singers Birzhan sal, Ykili Ybyyrai, Baluan Sholak, Koken Shakeev, famous writers Zhumagali Sain, Saken Zhunusov and many other prominent figures of literature and art of Kokshetau landAndesh Kurmanbayev, a veteran of the tax service, who took part in the event, noted that the exhibits and artifacts of the Museum characterize the national culture, ethnographic values and identity of the Kazakh people.Source : https://www.gov.kz/memleket/entities/kgd-akmola/press/news/details/1316062?lang=ru
The State Revenue Department for the Karaganda Region informs taxpayers about the compulsory termination of their activities
16.11.2026
📢 The State Revenue Department for the Karaganda Region informs taxpayers about the compulsory termination of their activities⚖️ In accordance with Article 109 of the Tax Code of the Republic of Kazakhstan, the compulsory termination of activities is предусмотрено for taxpayers included in the register of inactive taxpayers who meet the conditions established by law.🔎 Who is subject to compulsory termination of activities?Pursuant to paragraph 1 of Article 109, a taxpayer included in the register of inactive taxpayers is subject to compulsory termination of activities if, during the limitation period, the taxpayer simultaneously meets the following conditions:1️⃣ Has not independently submitted tax returns.2️⃣ Has not carried out export or import transactions.3️⃣ Has not made payments and/or transfers of money through bank accounts.4️⃣ Has not been registered for value-added tax (VAT) purposes.5️⃣ Has not acted as the head and/or founder of another legal entity or as a participant in joint entrepreneurship.6️⃣ Has not suspended the submission of tax returns.7️⃣ Has not owned property subject to property tax, vehicles subject to vehicle tax, or land subject to land tax, except for taxable items belonging to individuals.8️⃣ Has no outstanding social payment liabilities.9️⃣ Has no outstanding tax liabilities, payments to the budget, customs duties or taxes exceeding six times the monthly calculation index (MCI) in effect as of January 1 of the relevant financial year.⚠️ In which cases do these provisions not apply?The provisions of the first part of paragraph 1 of Article 109 do not apply to taxpayers:🔹 subject to tax monitoring;🔹 carrying out activities under a subsoil use contract;🔹 having outstanding notifications on the elimination of violations identified through desk audits or tax inspections, or notifications considered fulfilled through the submission of explanations, where such violations exist;🔹 subject to measures (seizures or restrictions) imposed by enforcement officers and/or other authorized bodies;🔹 who are or were parties to a foreign exchange contract relating to exports or imports for which foreign exchange control procedures aimed at the repatriation of national and/or foreign currency have not been completed;🔹 who have made payments and/or transfers of money through bank accounts during the limitation period.📌 What else should be taken into account?The period taken into account when including a taxpayer in the register of inactive taxpayers is also included in the period considered for the compulsory termination of activities.🏛️ How is compulsory termination of activities carried out?In accordance with paragraph 2 of Article 109 of the Tax Code of the Republic of Kazakhstan:⚖️ The compulsory termination of a taxpayer’s activities is carried out by the tax authority on the basis of a court decision that has entered into legal force, in accordance with the requirements of the laws of the Republic of Kazakhstan.📄 A taxpayer whose activities have been compulsorily terminated on the basis of a court decision that has entered into legal force is deregistered with the tax authority in accordance with the established tax registration procedure.✅ The State Revenue Department for the Karaganda Region recommends that taxpayers fulfil their tax obligations on time, submit tax returns within the prescribed deadlines, and ensure that their registration status remains up to date.🤝 Compliance with tax legislation is an important condition for the proper fulfilment of tax obligations. Source : https://www.gov.kz/memleket/entities/kgd-karaganda/press/news/details/1316065?lang=ru
Pilot Project for Business Support and Assistance Centres.
16.11.2026
The Department of State Revenue for Astana hereby informs that, starting from 1 September 2026, JSC “Entrepreneurship Development Fund ‘Damu’” will implement a pilot project to establish Business Support and Assistance Centres in the cities of Astana, Almaty and Shymkent, as well as in the Aktobe and North Kazakhstan regions.The Centres provide comprehensive support to small and medium-sized businesses facing crisis situations. Their operations are based on a “one-stop-shop” principle, whereby entrepreneurs receive assistance in identifying the nature of their problems, developing solutions, and obtaining support in liaising with relevant government authorities and financial institutions.Representatives of the territorial departments of state revenue and the regional Chambers of Entrepreneurs “Atameken” receive entrepreneurs at the Centres in accordance with an established schedule.For further information, please contact the regional branches of the Damu Fund in the regions listed above. Source : https://www.gov.kz/memleket/entities/kgd-astana/press/news/details/1316038?lang=ru
Kazakhstan’s Cultural and Business Centre Opens in Switzerland
15.11.2026
On 21 October 2026, the SwissKazakh Cultural and Business Centre was inaugurated in Schaffhausen, Switzerland. The centre was established on the initiative of Eurasia Group, with the support of the Embassy of the Republic of Kazakhstan in Switzerland, to promote trade, economic and cultural cooperation between the two countries.One of the centres key priorities will be to promote Kazakhstani products in Switzerland and other international markets. Particular emphasis will be placed on products from the metallurgical, agro-industrial, food and chemical industries. The centre will facilitate direct business contacts between Kazakhstani producers, foreign importers and retail chains, as well as support the development of investment cooperation. Another dedicated area of its activities will focus on promoting Kazakhstans history and culture.The opening ceremony was attended by Arman Shakkaliyev, Minister of Trade and Integration of the Republic of Kazakhstan; representatives of the authorities of the Canton of Schaffhausen; representatives of the Embassy of Kazakhstan in Switzerland and QazTrade JSC; Kazakhstani and Swiss entrepreneurs; and members of the academic community.Speaking at the event, Arman Shakkaliyev emphasised Kazakhstans interest in expanding economic cooperation with Switzerland, including attracting technology, developing industrial capabilities and implementing long-term joint projects.Nurlan Kulbatyrov, Chief Executive Officer of QazTrade JSC, presented Kazakhstans export and investment potential, as well as existing support mechanisms designed to help domestic producers enter the Swiss market.M. Zakhin, President of Eurasia Group AG, outlined the objectives behind establishing the centre and its role in fostering business ties between entrepreneurs from the two countries.Representatives of the Canton of Schaffhausen highlighted prospects for cooperation with Kazakhstan in business, agriculture and agricultural processing. Opportunities to strengthen scientific, educational and cultural ties were also discussed during the event.Kazakhstans Ambassador to Switzerland, K. Sarzhanov, presented key indicators of bilateral economic cooperation. Since 2005, Swiss investment in Kazakhstan has exceeded USD 36.5 billion. In 2025, bilateral trade turnover amounted to USD 1.5 billion.The initiative to establish the centre was launched by Eurasia Group, which operates in Kazakhstans agricultural machinery market. The groups total investment in Kazakhstan has reached USD 88.5 million. These funds have been directed towards developing service infrastructure, purchasing equipment and training specialists. Since 2025, the company has also been working to localise the production of John Deere agricultural machinery in Kazakhstan.Source : https://www.gov.kz/memleket/entities/mti/press/news/details/1315985?lang=ru
AGRICULTURAL COOPERATIVES: WHEN SHOULD I PAY 3%, 6%, OR 20% CPN?
15.11.2026
AGRICULTURAL COOPERATIVES: WHEN SHOULD I PAY 3%, 6%, OR 20% CPN?Starting from January 1, 2026, Kazakhstan has differentiated corporate income tax (CIT) rates for agricultural production cooperatives (SPCs).The main rule: The rate depends not just on the status of the cooperative or the OKED code, but on what exactly it does and where it gets its products from.3%Its products6%SEC activities20%Other activitiesWhen does 3% apply?If the cooperative is a direct producer of agricultural products.Examples:The SEC independently grows wheat and sells the crop.The cooperative breeds cattle and sells the raised breeding young.SEC produces its own milk, processes it into cheese, butter or other dairy products and sells the finished product.Condition: the products must be produced in-house by the cooperative.When is 6% applied?If the SEC carries out cooperative activities provided for by the Tax Code that do not fall under the 3% rate.Examples:The cooperative buys the milk produced by its members, processes it and sells the finished products.SEC harvests, stores, and sells grain grown by cooperative members.The cooperative provides its members with zootechnical and other auxiliary services for the production of agricultural products.The SEC sells to its members goods for the production and processing of agricultural products.Important: products purchased from SEC members do not become products of the cooperative's own production. Therefore, the processing of such raw materials refers to the rate of 6%, not 3%.When is 20% applied?If the SEC receives income from other activities that do not comply with the terms of the 3% or 6% rates.Examples:The SEC buys milk from third-party suppliers who are not members of the cooperative, processes and sells products as part of its independent activities.The cooperative provides commercial zootechnical services to third-party organizations.SEC is engaged in independent trading or other activities not provided for in Article 16 of the Tax Code.For such transactions, the rate is determined taking into account the actual nature of the activity and possible special provisions of the Tax Code.Let's look at one example.SEC Bereke is engaged in the production and processing of milk.Own milk → cheese → saleKPN 3%Milk from SEC members → cheese → saleKPN 6%Milk from third-party suppliers → cheese → saleCPN of 20% if the activity does not fall under preferential categoriesWhat if a cooperative conducts several types of activities at once?It is necessary to keep separate tax records for activities that are taxed at different rates.This means that you need to separately account for the relevant income, expenses and calculate taxable income.Three mistakes to avoid1. Consider that any SEC is automatically entitled to a 6% rate on all income.2. Apply 3% to milk processing only because it was purchased from cooperative members.3. Focus solely on the OKED code, without taking into account the actual nature of the activity.Save this post and share it with the heads of agricultural cooperatives! The correct determination of the CPI rate will help to avoid errors in tax reporting and additional charges.Department of State Revenue for Kostanay regionBasis: Articles 16, 211, 345 and 357 of the Tax Code of the Republic of Kazakhstan dated July 18, 2025 No. 214-VIII.Source : https://www.gov.kz/memleket/entities/kgd-kostanay/press/news/details/1315968?lang=ru