Corporate Income Tax Advance Payments
01.10.2026 07:46:30 301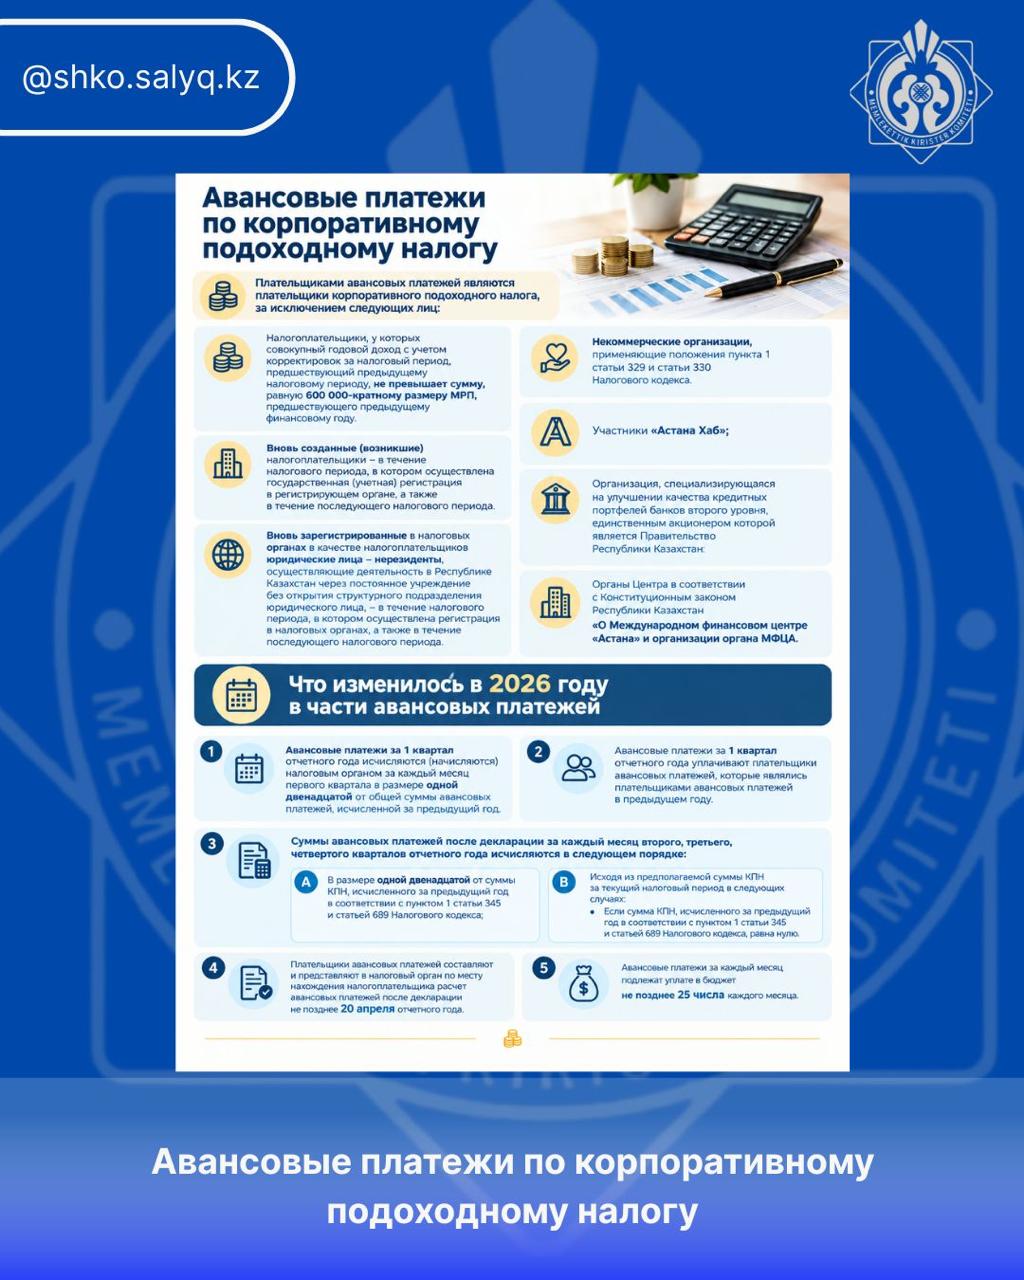
Corporate income tax payers are required to make advance payments, except for the following taxpayers:
Taxpayers whose aggregate annual income, including adjustments, for the tax period preceding the previous tax period does not exceed an amount equal to 600,000 times the Monthly Calculation Index (MCI) applicable to the year preceding the previous financial year;
Newly established (newly formed) taxpayers — during the tax period in which state (registration) registration is carried out with the registering authority, as well as during the subsequent tax period;
Legal entities — non-residents newly registered with the tax authorities as taxpayers carrying out activities in the Republic of Kazakhstan through a permanent establishment without establishing a structural subdivision of the legal entity — during the tax period in which registration with the tax authorities is carried out, as well as during the subsequent tax period;
Non-profit organizations applying the provisions of Paragraph 1 of Article 329 and Article 330 of the Tax Code;
Participants of Astana Hub;
An organization specializing in improving the quality of loan portfolios of second-tier banks, whose sole shareholder is the Government of the Republic of Kazakhstan;
Bodies of the Centre in accordance with the Constitutional Law of the Republic of Kazakhstan “On the Astana International Financial Centre”, as well as organizations of an AIFC body.
What Changed in 2026 Regarding Advance Payments?
Advance payments for the first quarter of the reporting year are calculated (assessed) by the tax authority for each month of the first quarter in the amount of one-twelfth of the total amount of advance payments calculated for the previous year.
Advance payments for the first quarter of the reporting year are paid by taxpayers that were subject to advance payments in the previous year.
After the tax return is filed, the amounts of advance payments for each month of the second, third and fourth quarters of the reporting year are calculated as follows:
In the amount of one-twelfth of the corporate income tax (CIT) amount calculated for the previous year in accordance with Paragraph 1 of Article 345 and Article 689 of the Tax Code;
Based on the estimated amount of CIT for the current tax period in the following case:
if the amount of CIT calculated for the previous year in accordance with Paragraph 1 of Article 345 and Article 689 of the Tax Code is zero.
Taxpayers subject to advance payments must prepare and submit the calculation of advance payments after the tax return to the tax authority at the taxpayer's location no later than April 20 of the reporting year.
Advance payments for each month must be paid to the budget no later than the 25th day of each month.
Source : https://www.gov.kz/memleket/entities/kgd-vko/press/news/details/1301909?lang=ru